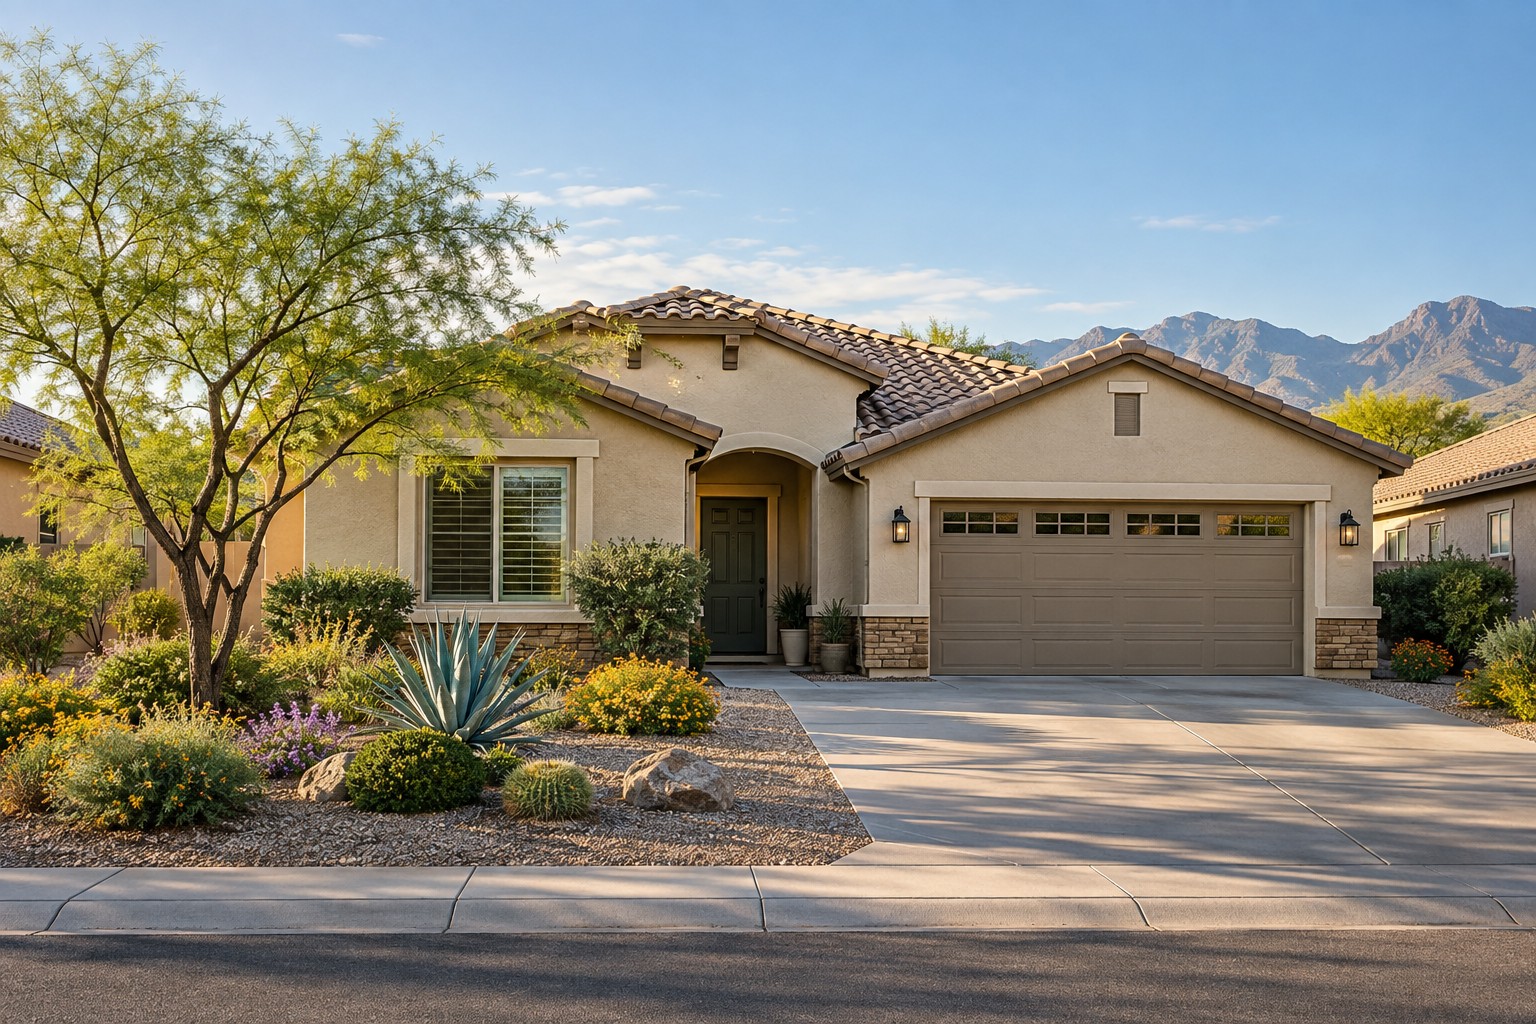
19929 W Annika Drive, Litchfield Park
Surprise & the West Valley
VA Assumable Homes in Surprise & the West Valley
The right home may come with a loan worth keeping. Explore local listings with existing VA financing, then let Todd help you check the loan details and the seller's plans.
Start with the home. Compare the rate, upfront funds and timeline.
Start your search
Homes with Existing VA Financing
See a home you like? Open the listing for photos and details, or send Todd the address to ask about its existing loan.
What this search shows: Active listings marked Current Financing: VA in the MLS. This is a starting point, not a list of verified assumption offers. The seller's participation, loan terms and servicer approval still need to be confirmed.
Open the full search for current listings, photos and property details.
The opportunity
An existing loan's terms
An approved assumption transfers the remaining loan balance and its terms to the buyer. An attractive existing rate can make a home worth a closer look.
The numbers
More than the interest rate
Compare the purchase price, remaining balance, funds needed at closing and total monthly housing costs.
The next step
Verify before you commit
Todd helps gather property and seller information. The loan servicer determines the assumption requirements and approval.
Compare the payment and upfront funds
What Could a 3.5% VA Assumption Change?
Compare an illustrative 3.5% assumption with a new loan at an illustrative 6.5%. Both scenarios finance the same amount. Adjust the rates and terms to see how the monthly principal and interest changes.
Real listing price. Illustrative loan terms. This example starts with the $415,000 asking price observed September 25, 2026 for 19929 W Annika Drive, Litchfield Park (MLS #7085248). The home's interest rate, remaining balance, loan term and assumption availability have not been verified. All loan inputs below are examples, not this home's confirmed terms or a current lender quote. Price and availability may change.
Listing courtesy of OfferPad Brokerage, LLC. Property details and current availability are on the listing page.
For the assumption, use the seller's remaining balance.
Funds toward the price, before other costs
Purchase price minus loan amount. Both examples use the same contribution toward the price; fees and closing costs can differ.
Illustrative existing VA loan
Assume the Remaining Loan
Per month · principal & interest only
Illustrative new loan
Start a New Mortgage
Per month · principal & interest only
In this example, the assumption's monthly principal and interest is $433.76 lower.
Planning illustration using fixed rates and fully amortizing monthly payments. Excludes taxes, insurance, HOA fees, mortgage insurance, funding fees, other closing costs and credits. Interest rate is not APR. Compare repayment terms as well as payments; a lower monthly payment alone does not establish the better overall choice. This is not a loan offer, approval or cash-to-close quote.
Planning a move to Luke AFB? Use the Luke AFB housing-budget guide to compare your complete monthly costs alongside the loan payment.
More places. More options.
Surprise and the Surrounding West Valley
Compare homes across 13 communities. Share your preferred location, price range and home features so Todd can help you build a useful shortlist.
Surprise & nearby
Surprise, Waddell, El Mirage, Youngtown and Wittmann.
North & northeast
Peoria, Glendale, Sun City and Sun City West.
More West Valley communities
Explore homes in Litchfield Park, Goodyear, Avondale and Buckeye.
Some homes are in age-restricted communities. Check occupancy requirements, HOA fees and community rules for each property.
Choose your city and price range →From browsing to a plan
Four Checks Before You Make an Offer
A good assumption opportunity needs to work as a home purchase, too. Compare the home's condition, location and price with other options before focusing on the loan. The Surprise home buyer guide explains the broader purchase process, from financing through inspections and closing.
A listing that accepts new VA financing does not necessarily have an existing VA loan to assume. This page uses the MLS Current Financing field.
- Confirm the seller's plansAsk whether the seller is willing to pursue an assumption and who services the existing loan.
- Get the loan detailsRequest the balance, rate, remaining term and payment breakdown. Include taxes, insurance and HOA costs in your budget.
- Review funds and timingDiscuss the price-to-balance gap, closing costs, required documents and expected processing time with the servicer.
- Address the seller's VA benefitConfirm release of liability and whether substitution of entitlement is part of the transaction.
Clear answers before you buy
VA Loan Assumption Questions
Understand what carries over, what needs approval and which numbers to check.
Ask Todd About a Home →Are these homes confirmed VA assumption opportunities?
Not yet. These listings report existing VA financing in the MLS. They do not confirm a particular interest rate, loan balance or seller agreement to an assumption. Todd can contact the listing agent to help verify those details.
Do I have to be a veteran to assume a VA loan?
No. A qualified non-veteran may also assume a VA loan. The buyer must meet VA credit and income standards. A seller may prefer an eligible veteran who can substitute sufficient entitlement, so discuss the seller's requirements early.
Will I keep the seller's interest rate and payment?
An assumption generally continues the existing loan's rate and remaining repayment term. Verify whether the loan has a fixed or adjustable rate. Taxes and insurance can change, so the seller's current total payment is not a guarantee of your future housing cost.
How much money will I need upfront?
Start with the agreed price minus the remaining loan balance, then account for closing costs and credits. VA lists a 0.5% funding fee for assumptions, unless an exemption applies. Ask the servicer for a written estimate of all applicable fees. Assuming a VA loan does not automatically mean no money is needed at closing.
How long does a VA loan assumption take?
Timing depends on the servicer, the completeness of the application and any additional approvals. Ask for the document checklist and current processing estimate before setting a closing date. A buyer's preapproval for a new mortgage does not replace assumption approval.
What happens to the seller's VA entitlement?
Release of liability and restoration of entitlement are separate issues. Entitlement generally remains tied to the loan unless an eligible veteran with sufficient entitlement completes an approved substitution. Sellers should confirm both with their servicer before agreeing to an assumption.
Can I narrow the search or ask about another home?
Yes. Use Customize My Search to adjust city, price and features while keeping Current Financing set to VA. You can also send Todd any listing link, address or MLS number and ask him to check the existing loan information.
Official VA resources: Assumptions & seller entitlement (PDF) · Funding fees & closing costs · VA homebuyer's guide (PDF)
Local guidance. A practical next step.
Found a Home? Let's Check the Details.
Send Todd the address or MLS number, your target budget and moving timeline. He can ask the listing agent about the existing loan and seller's plans, then help you decide whether to take a closer look.
Todd Pooler · 21-year U.S. Army veteran · REALTOR®, Realty ONE Group
Keep exploring
Continue Your West Valley Home Search
Browse more homes below, or open the full results to view all matching listings.
MLS-reported VA financing. Availability, loan details and assumption eligibility require verification.
Surprise & West Valley Homes with Existing VA Loans
Copyright 2026 Arizona Regional Multiple Listing Service, All rights reserved. The data relating to real estate for sale on this website comes in part from the Arizona Regional Multiple Listing Service. All information deemed reliable but not guaranteed and should be independently verified. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) nor Arizona Regional Multiple Listing Service shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless.